How to Tokenize Funds and Capital Markets Products in Singapore
Learn how Singapore tokenization projects connect capital markets regulation, fund structures, investor eligibility, settlement and custody.
Introduction
Singapore's approach to tokenized capital markets products focuses on economic substance and the activities performed around the product. The practical question is what the investor receives and what each provider does. A token that represents a capital markets product needs to be evaluated within that framework.
For a fund manager or asset owner, this creates a useful planning discipline. Define the investment, intended buyers and servicing model first. Then decide how distributed ledger technology could improve distribution, ownership records or settlement.
Classify the Product and Build the Structure
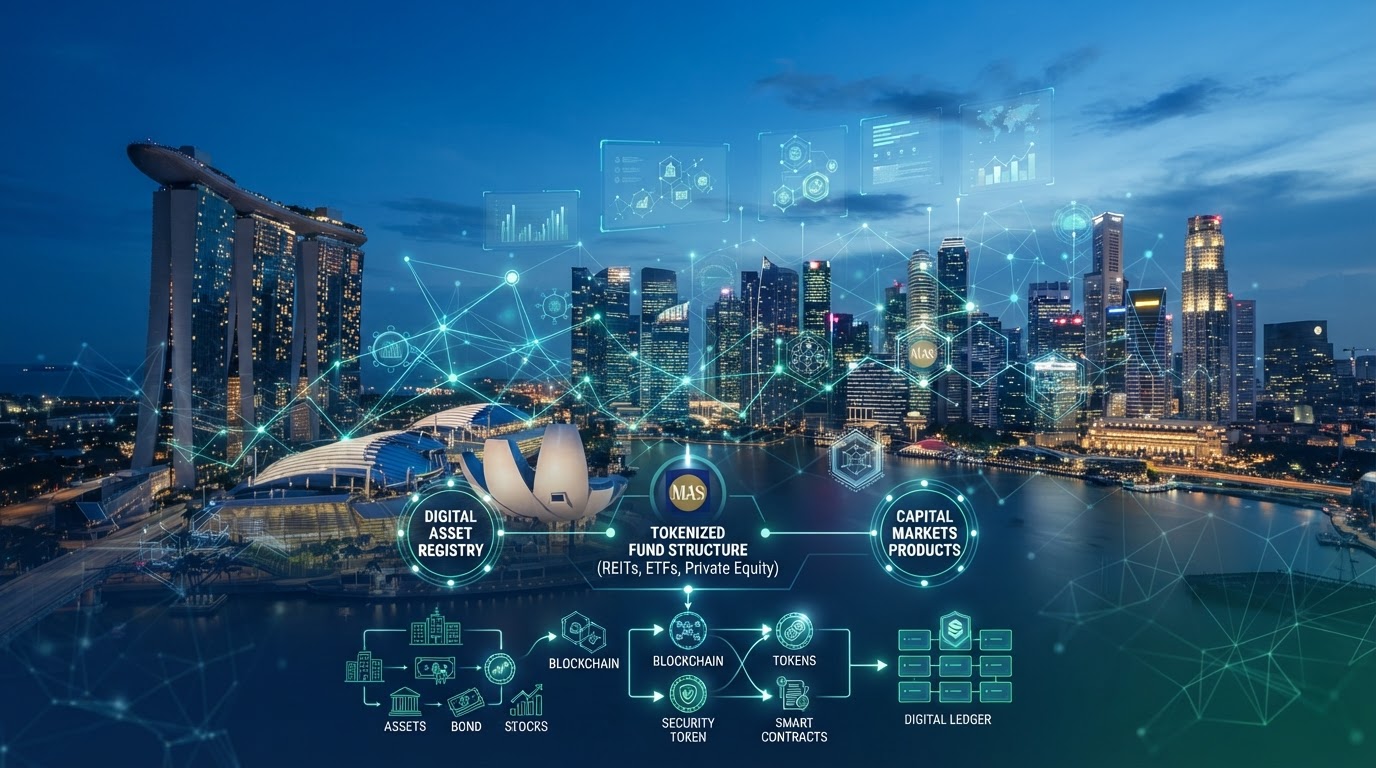
Identify whether the token represents shares, debt, units in a collective investment scheme or another regulated product. Distinguish that analysis from payment services questions that may arise when the structure uses digital payment tokens or other settlement arrangements. MAS's tokenization guide covers both issuance and activities across the product lifecycle.
Determine where the assets will be held and which entity owes obligations to investors. For a private credit fund, document the lending strategy, borrower underwriting, valuation, concentration limits and default management. Tokenization should make these features easier to administer and explain.
Choose Distribution and Provider Permissions
Specify the investor category and the jurisdictions where marketing will occur. Identify the applicable offering requirements or exemptions and ensure the distribution process meets their conditions. Assess the permissions of the manager, distributor, adviser, custodian and any market operator separately.
Prepare a simple service map that names each provider and the activity for which it is responsible. Ask providers to show how their permissions support the proposed product and client type. A technology supplier may be capable of issuing tokens without being authorised to distribute the investment.
Make Ownership and Settlement Consistent
Project Guardian's industry report on operationalising tokenized funds describes different register models, legal considerations and practical fund workflows. Its case studies are useful design references, rather than approvals for unrelated products.
Decide which record establishes the investor's interest and how subscriptions, transfers and redemptions update it. Reconcile token supply with issued units. Where more than one blockchain is used, document how tokens are moved or replaced and prevent duplicate claims. Establish responsibility for any bridge or messaging service.
Pilot a Complete Lifecycle
Consider a hypothetical Singapore-managed private credit fund offering tokenized units to an eligible investor group. The token represents a fund interest. The underlying loan assets, security arrangements and collection process remain within the fund's operating structure.
Run a pilot covering investor verification, cash receipt, token allocation, income payments, transfer restrictions and a redemption request. If loans are illiquid, align redemption terms with available cash and realistic sale options. Explain how a blockchain outage or compromised wallet affects the investor's ability to transact.
Review tax reporting, data protection, technology outsourcing and provider failure before accepting subscriptions. Measure the pilot against a conventional process: reconciliation time, error rates, servicing effort and investor access. Singapore's institutional experimentation provides useful operating lessons, but each issuer still needs its own legal analysis and a financially sustainable product.
Sources
- MAS Guide on the Tokenisation of Capital Markets Products
- Project Guardian Asset and Wealth Management Industry Group Operationalising Tokenised Funds